The chemical sector, which underpins the production of everyday goods and materials across the global economy, relies on nature for many of its operations and innovations, including water, biomass, mineral resources, energy inputs and feedstocks. From electronics to vehicles, textiles to pharmaceuticals, more than 95% of all manufactured products and materials rely on industrial chemical processes.
The sector, while essential to the products and materials used across society, is also a contributor to nature loss. The sector’s complex value chain brings unique challenges in identifying and managing nature-related impacts and dependencies. For example, they occur across multiple value chain stages, from the extraction of fossil-based, mineral and bio-based feedstocks, through manufacturing and distribution, to the use, disposal and recycling of chemical products. These activities can contribute to pressures on nature, including pollution, freshwater use, greenhouse gas emissions, land-use change and resource depletion.
Advancing the nature-positive agenda offers a strategic opportunity for the sector. By integrating nature considerations into decision-making across value chains, chemical companies can drive innovation, reduce environmental impacts, strengthen resilience to emerging risks and expectations, and support the transition to a more sustainable and circular economy.
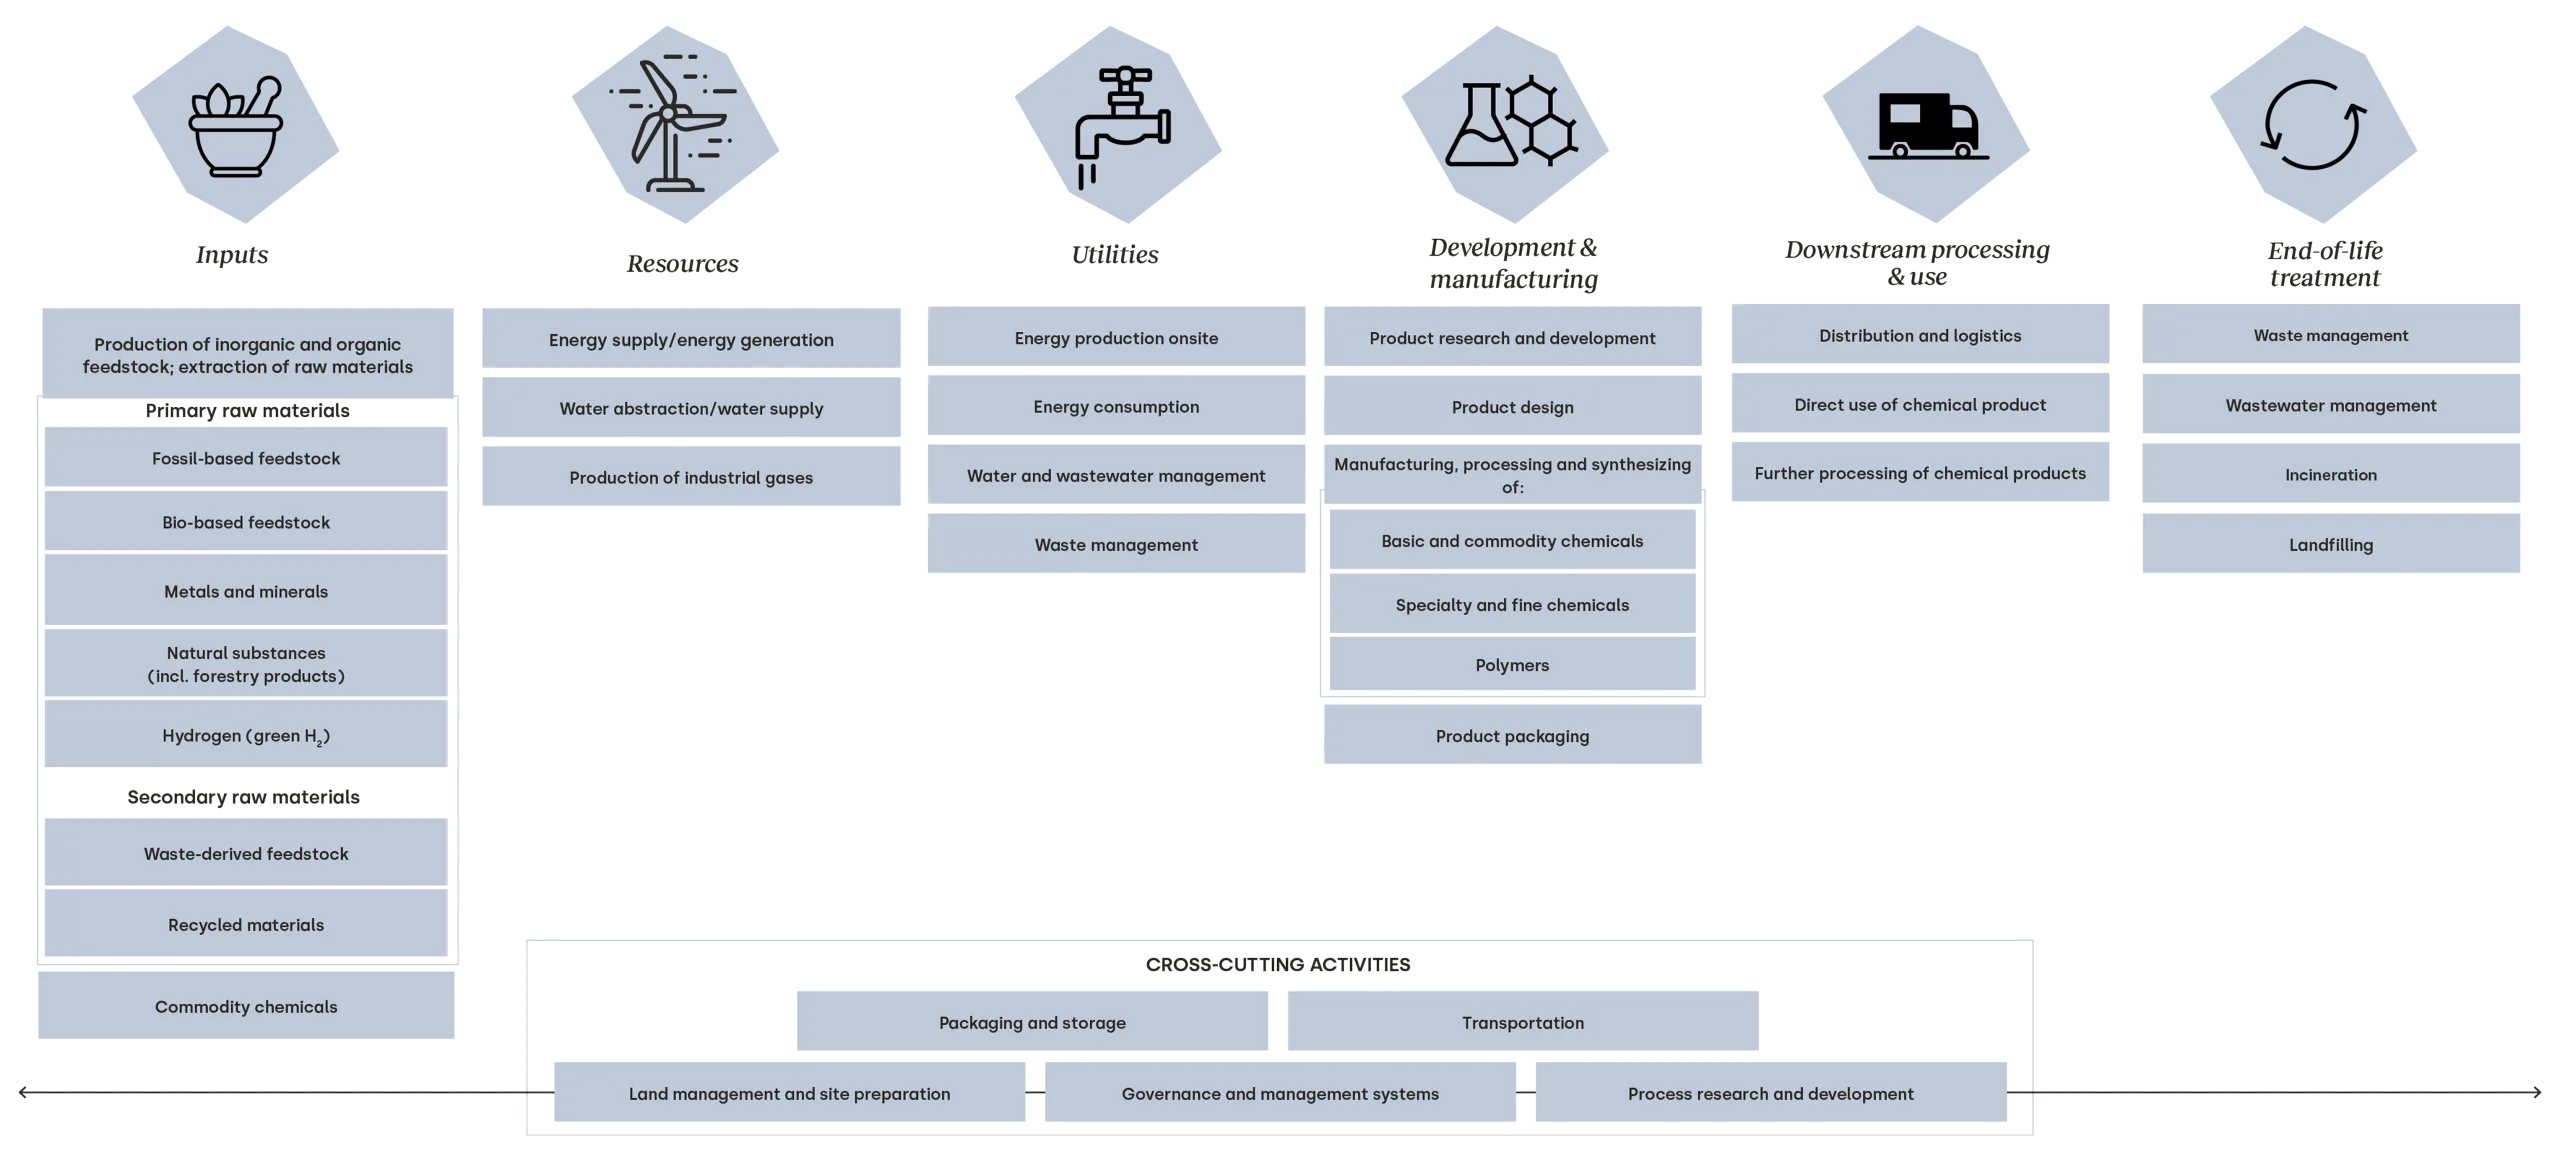
Chemical sector value chain
The chemical sector value chain encompasses a variety of processes. These range from inputs such as fossil-based and bio-based feedstocks, metals, minerals and recycled materials, through manufacturing and product development, to downstream processing, use and end-of-life treatment.
The value chain mapping aligns with WEF’s Nature Positive: Role of the Chemical Sector, Business for Nature’s overview Chemicals: Sector actions towards a nature positive future, and TNFD’s Additional Guidance by sector. It has also been refined through input from WBCSD working group members.
Dependencies, impacts, risks and opportunities
A sector level overview of dependencies, impacts, risks and opportunities (DIROs) provides a useful foundation for a company level materiality assessment because it highlights the typical DIROs relevant to companies operating in the same sector.
The DIROs capture how businesses in a sector interact with nature – relying on and impacting ecosystem services – and how these translate into risks and opportunities.
Companies should do a company-level materiality assessment – as recommended by the Natural Capital Protocol, SBTN and TNFD frameworks – to evaluate how the potential sector-level DIROs apply to the specific context of that company. The materiality assessment provides greater visibility into the company’s relationship with nature, enabling it to:
- Identify and manage risks;
- Uncover new business opportunities;
- Respond effectively to evolving investor and regulatory expectations.
This ultimately helps future-proof the business.
Methodologies for company-level materiality assessments include the Taskforce on Nature-related Financial Disclosures Guidance on the identification and assessment of nature-related issues: the LEAP approach and Science Based Targets Network’s Step 1: Assess your impacts on nature. The screening helps prioritize a more granular assessment of your company’s DIROs.
Dependencies and impacts in the chemical sector
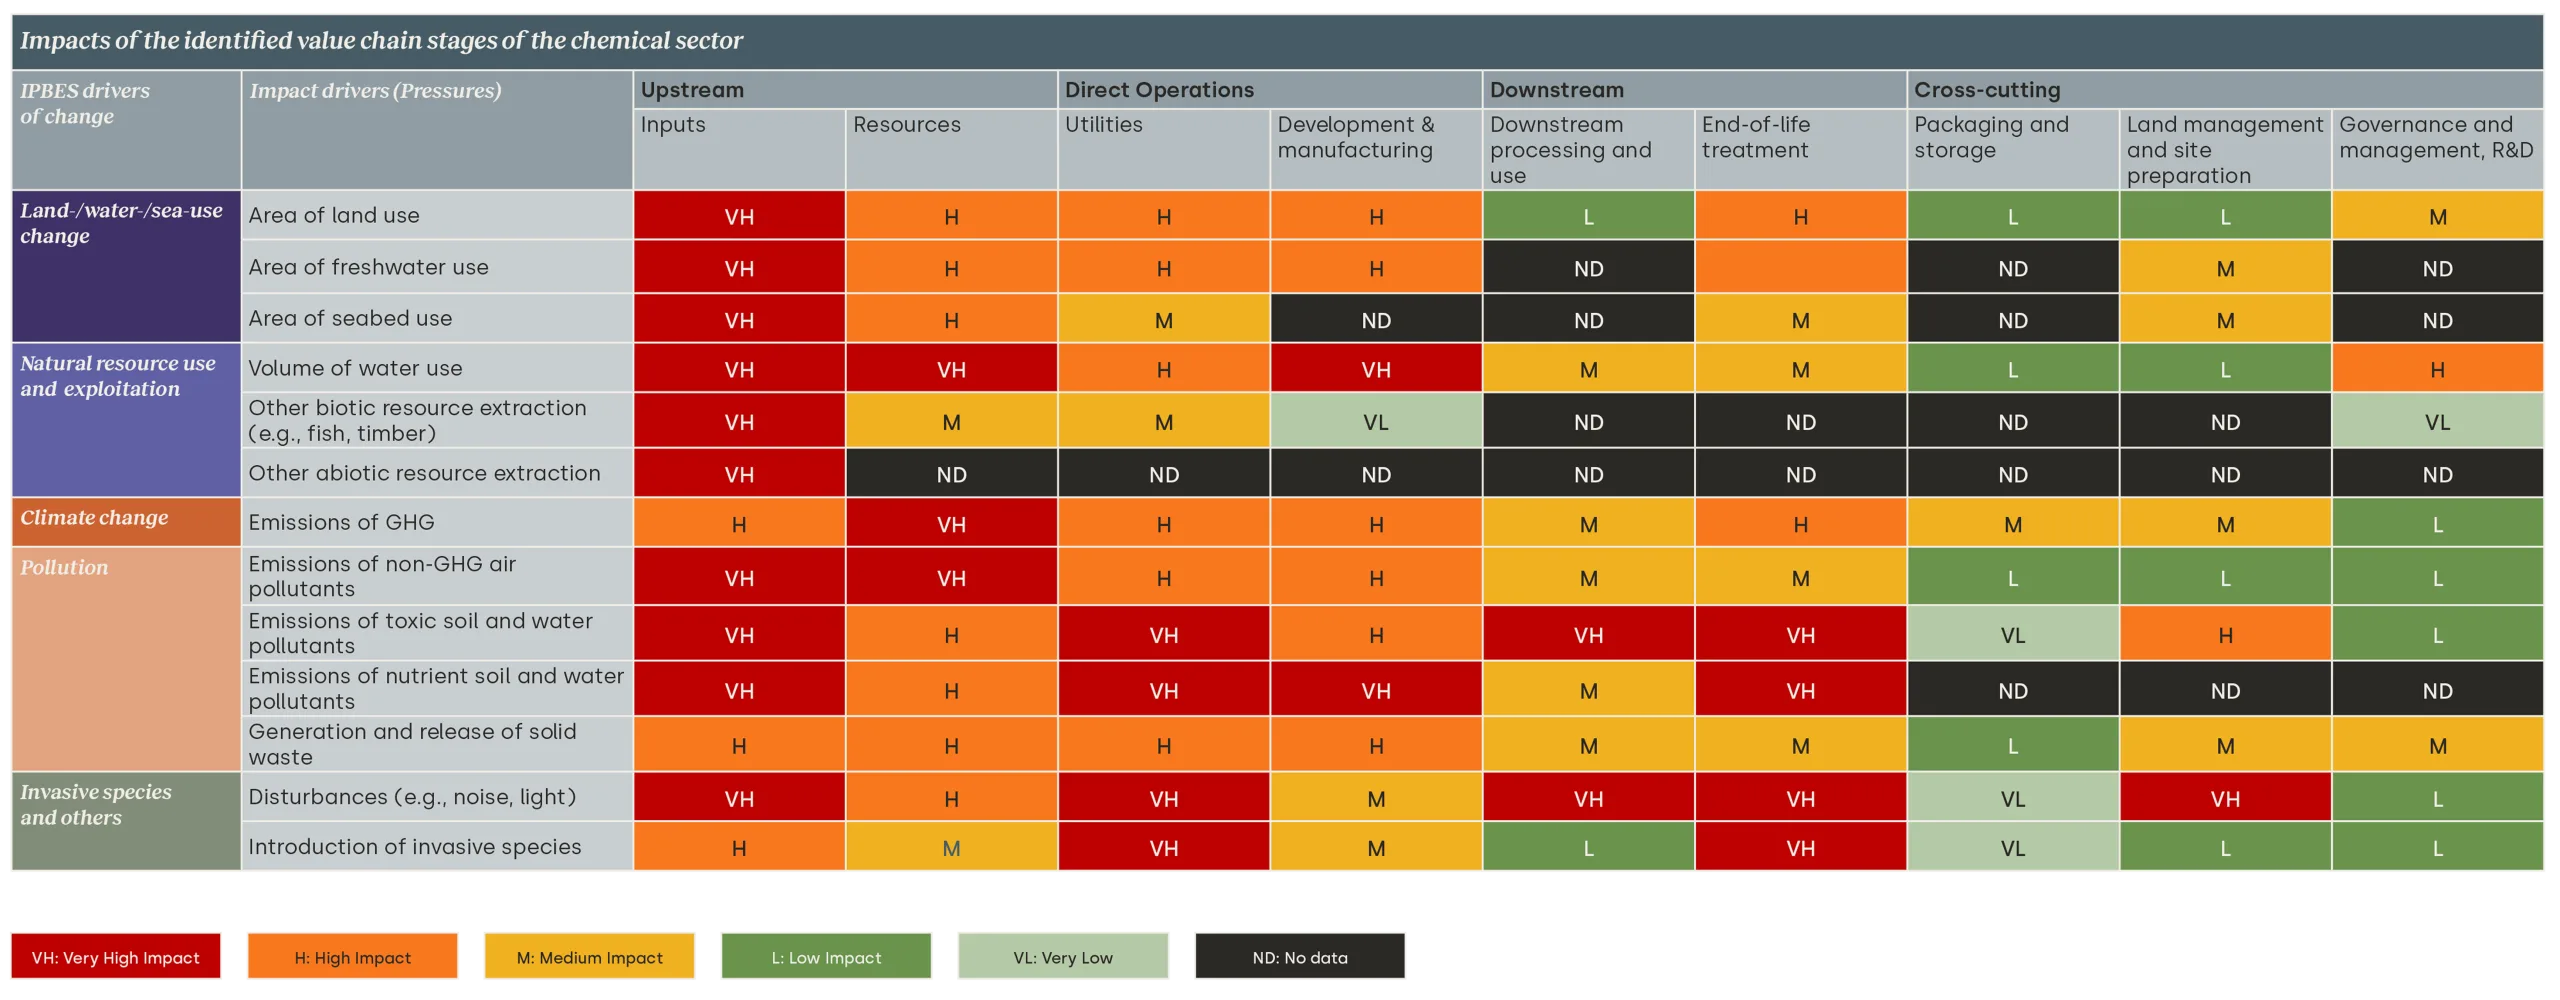
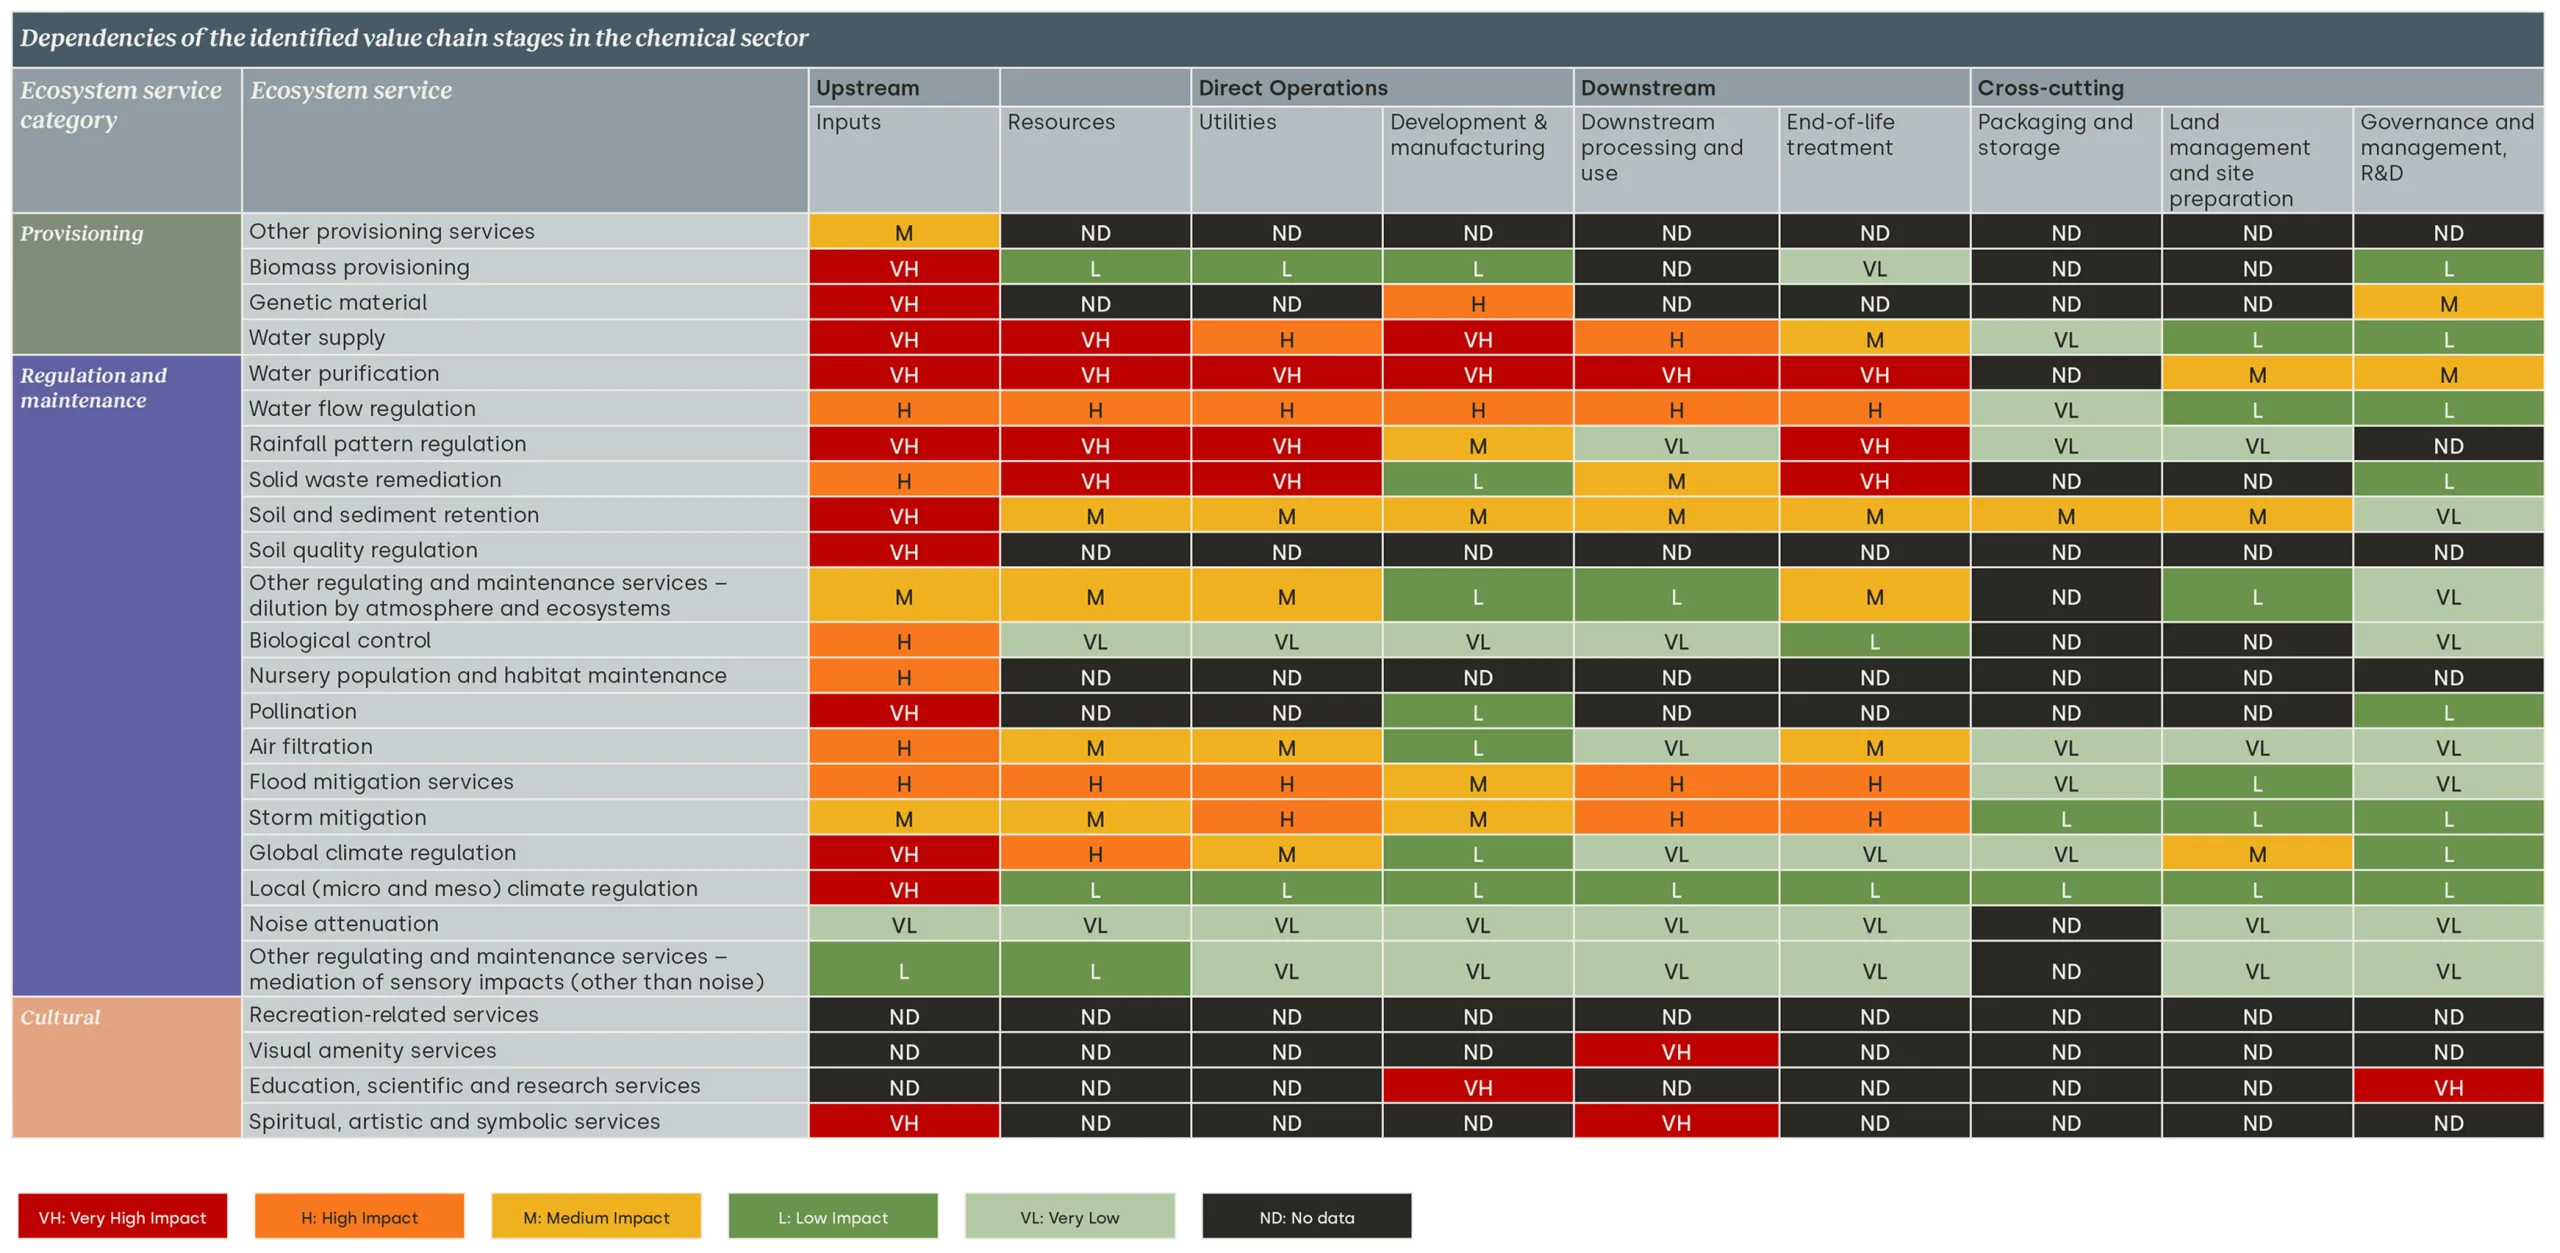
A system-level overview of dependencies and impacts provides a useful foundation for a company-level materiality screening. It highlights the typical dependencies and impacts relevant to companies operating in the same sector. Below are the top dependencies and impacts identified for the chemicals system.
The tables provide a complete list of potential nature-related impacts and dependencies, where they are likely to occur in the chemical value chain and their potential materialities. The list is the result of a generalized assessment and will require further risk and opportunity evaluation before companies use it to inform the development of actions to halt and reverse nature loss and targets. The materiality ratings in the diagrams are based on the 2024 version of the ENCORE (Exploring Natural Capital Opportunities, Risks and Exposure) database.
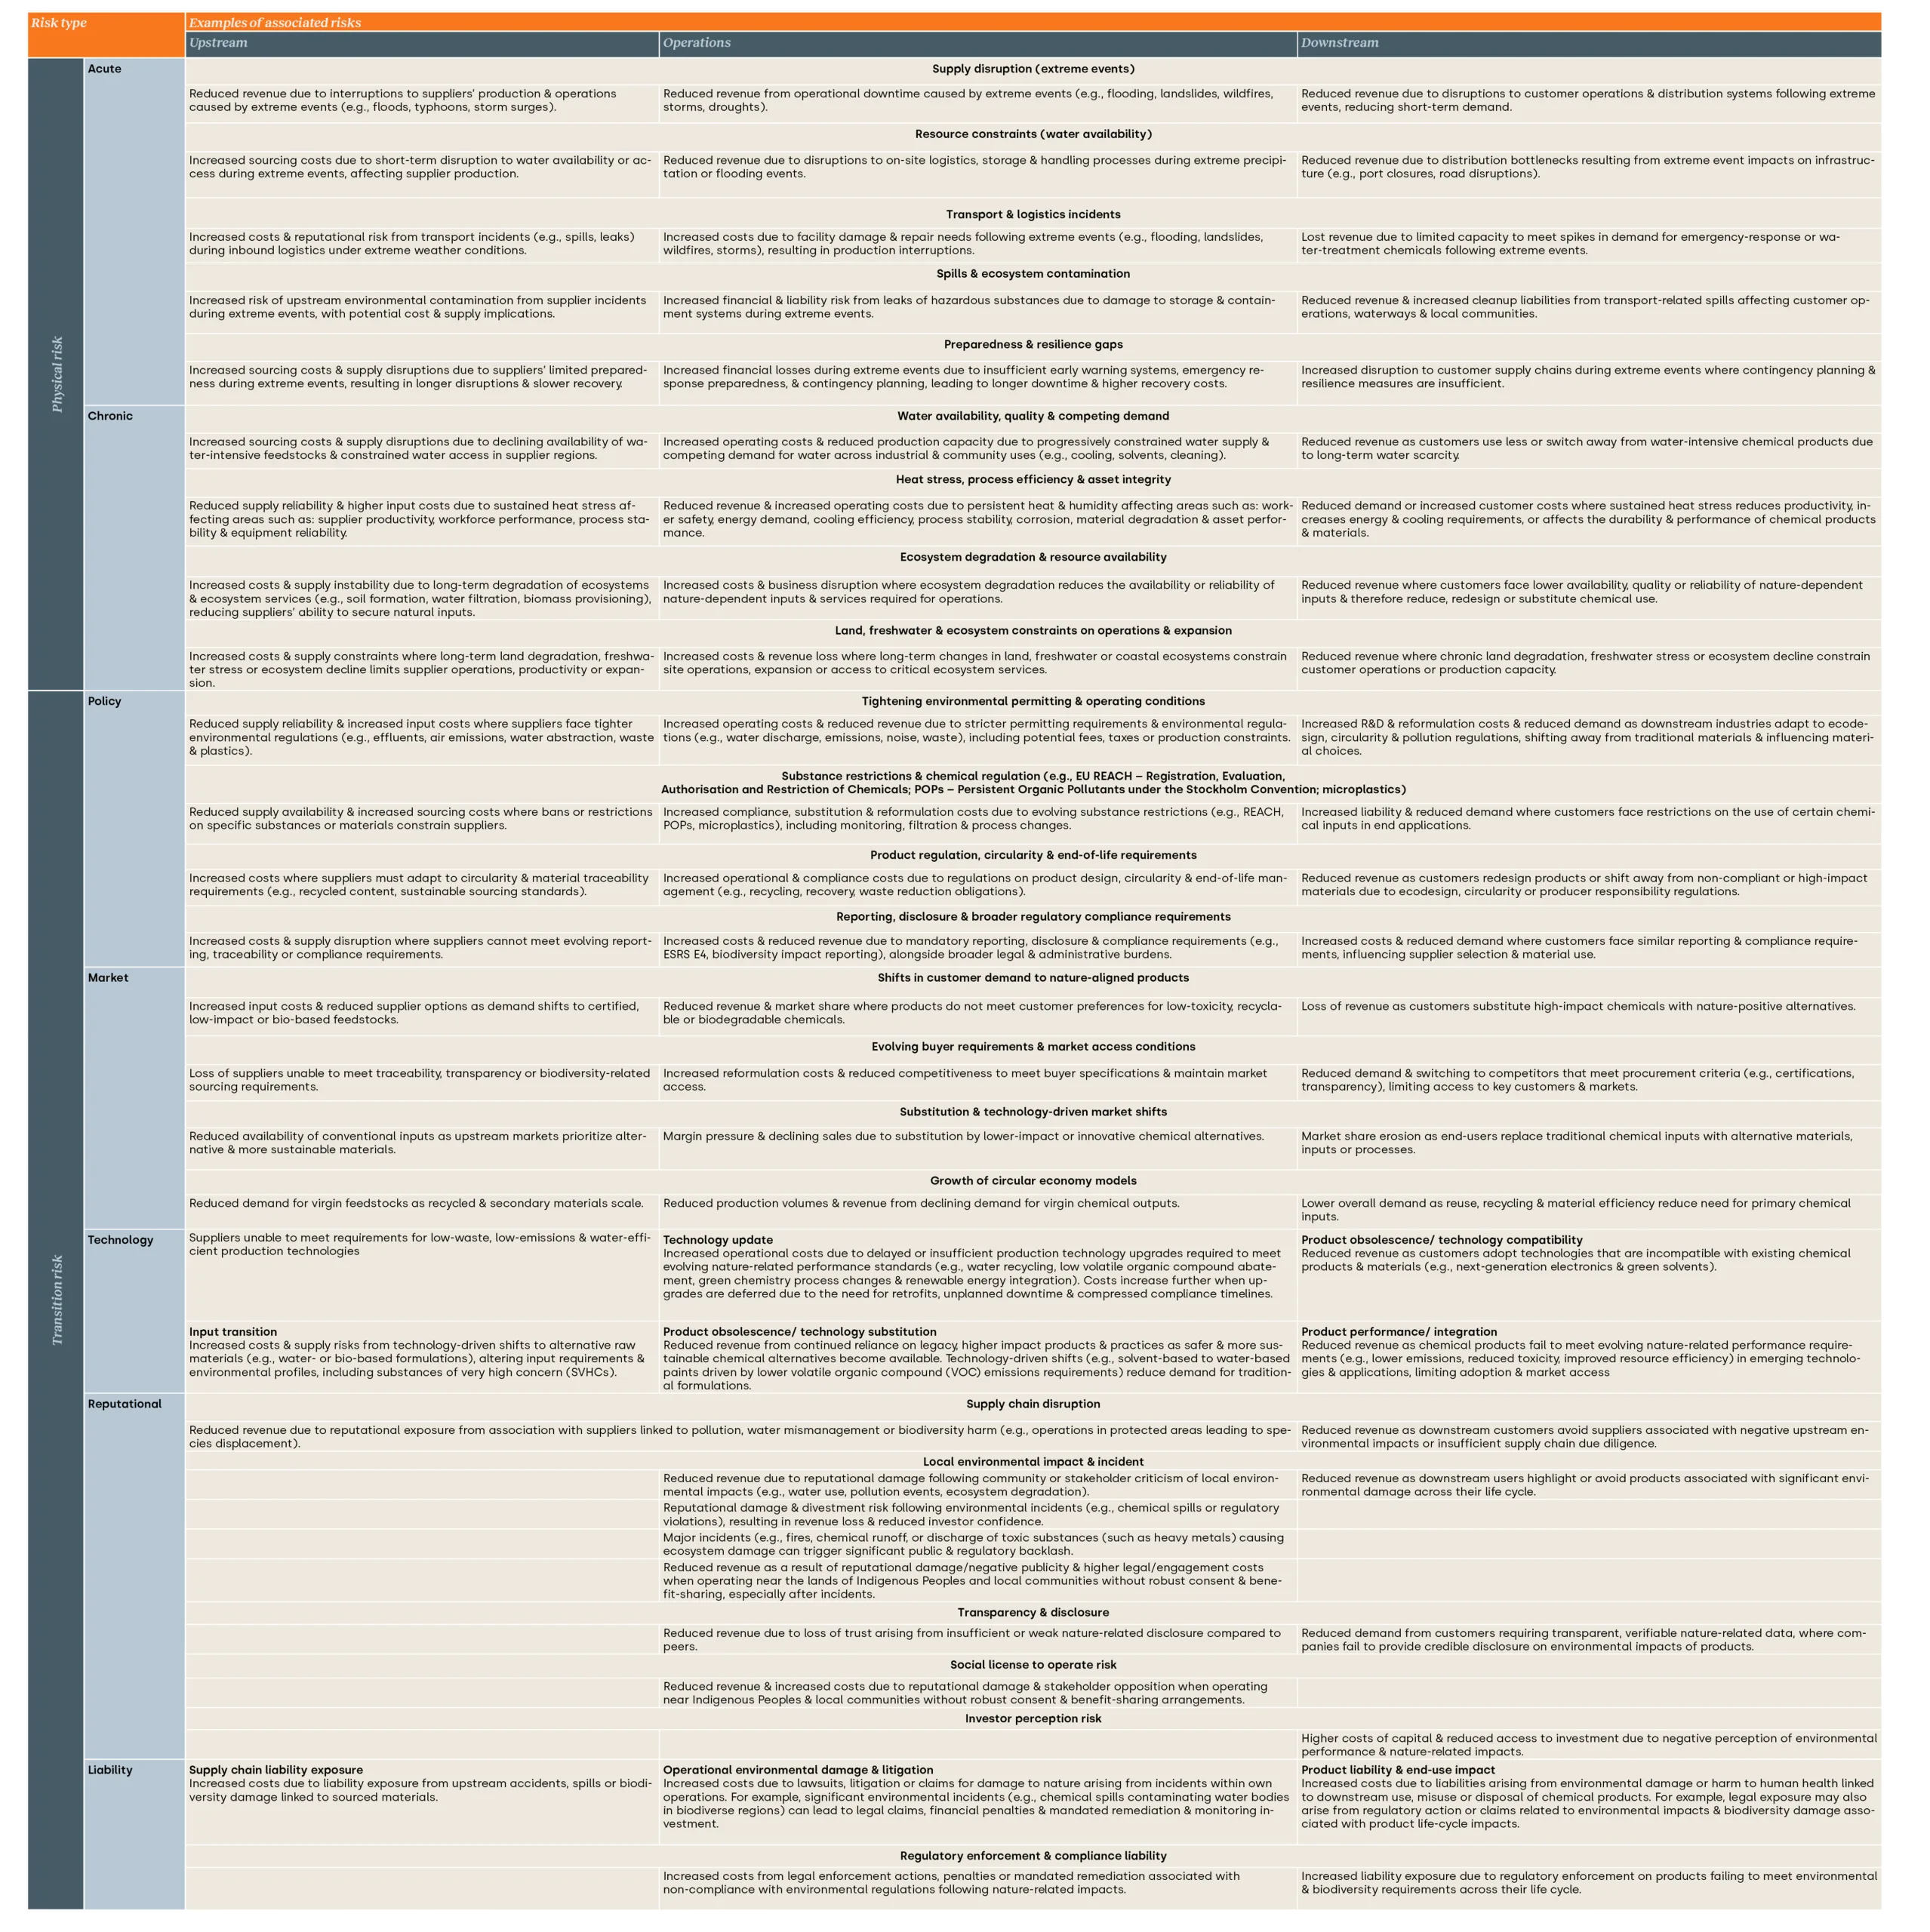
Risks & opportunities
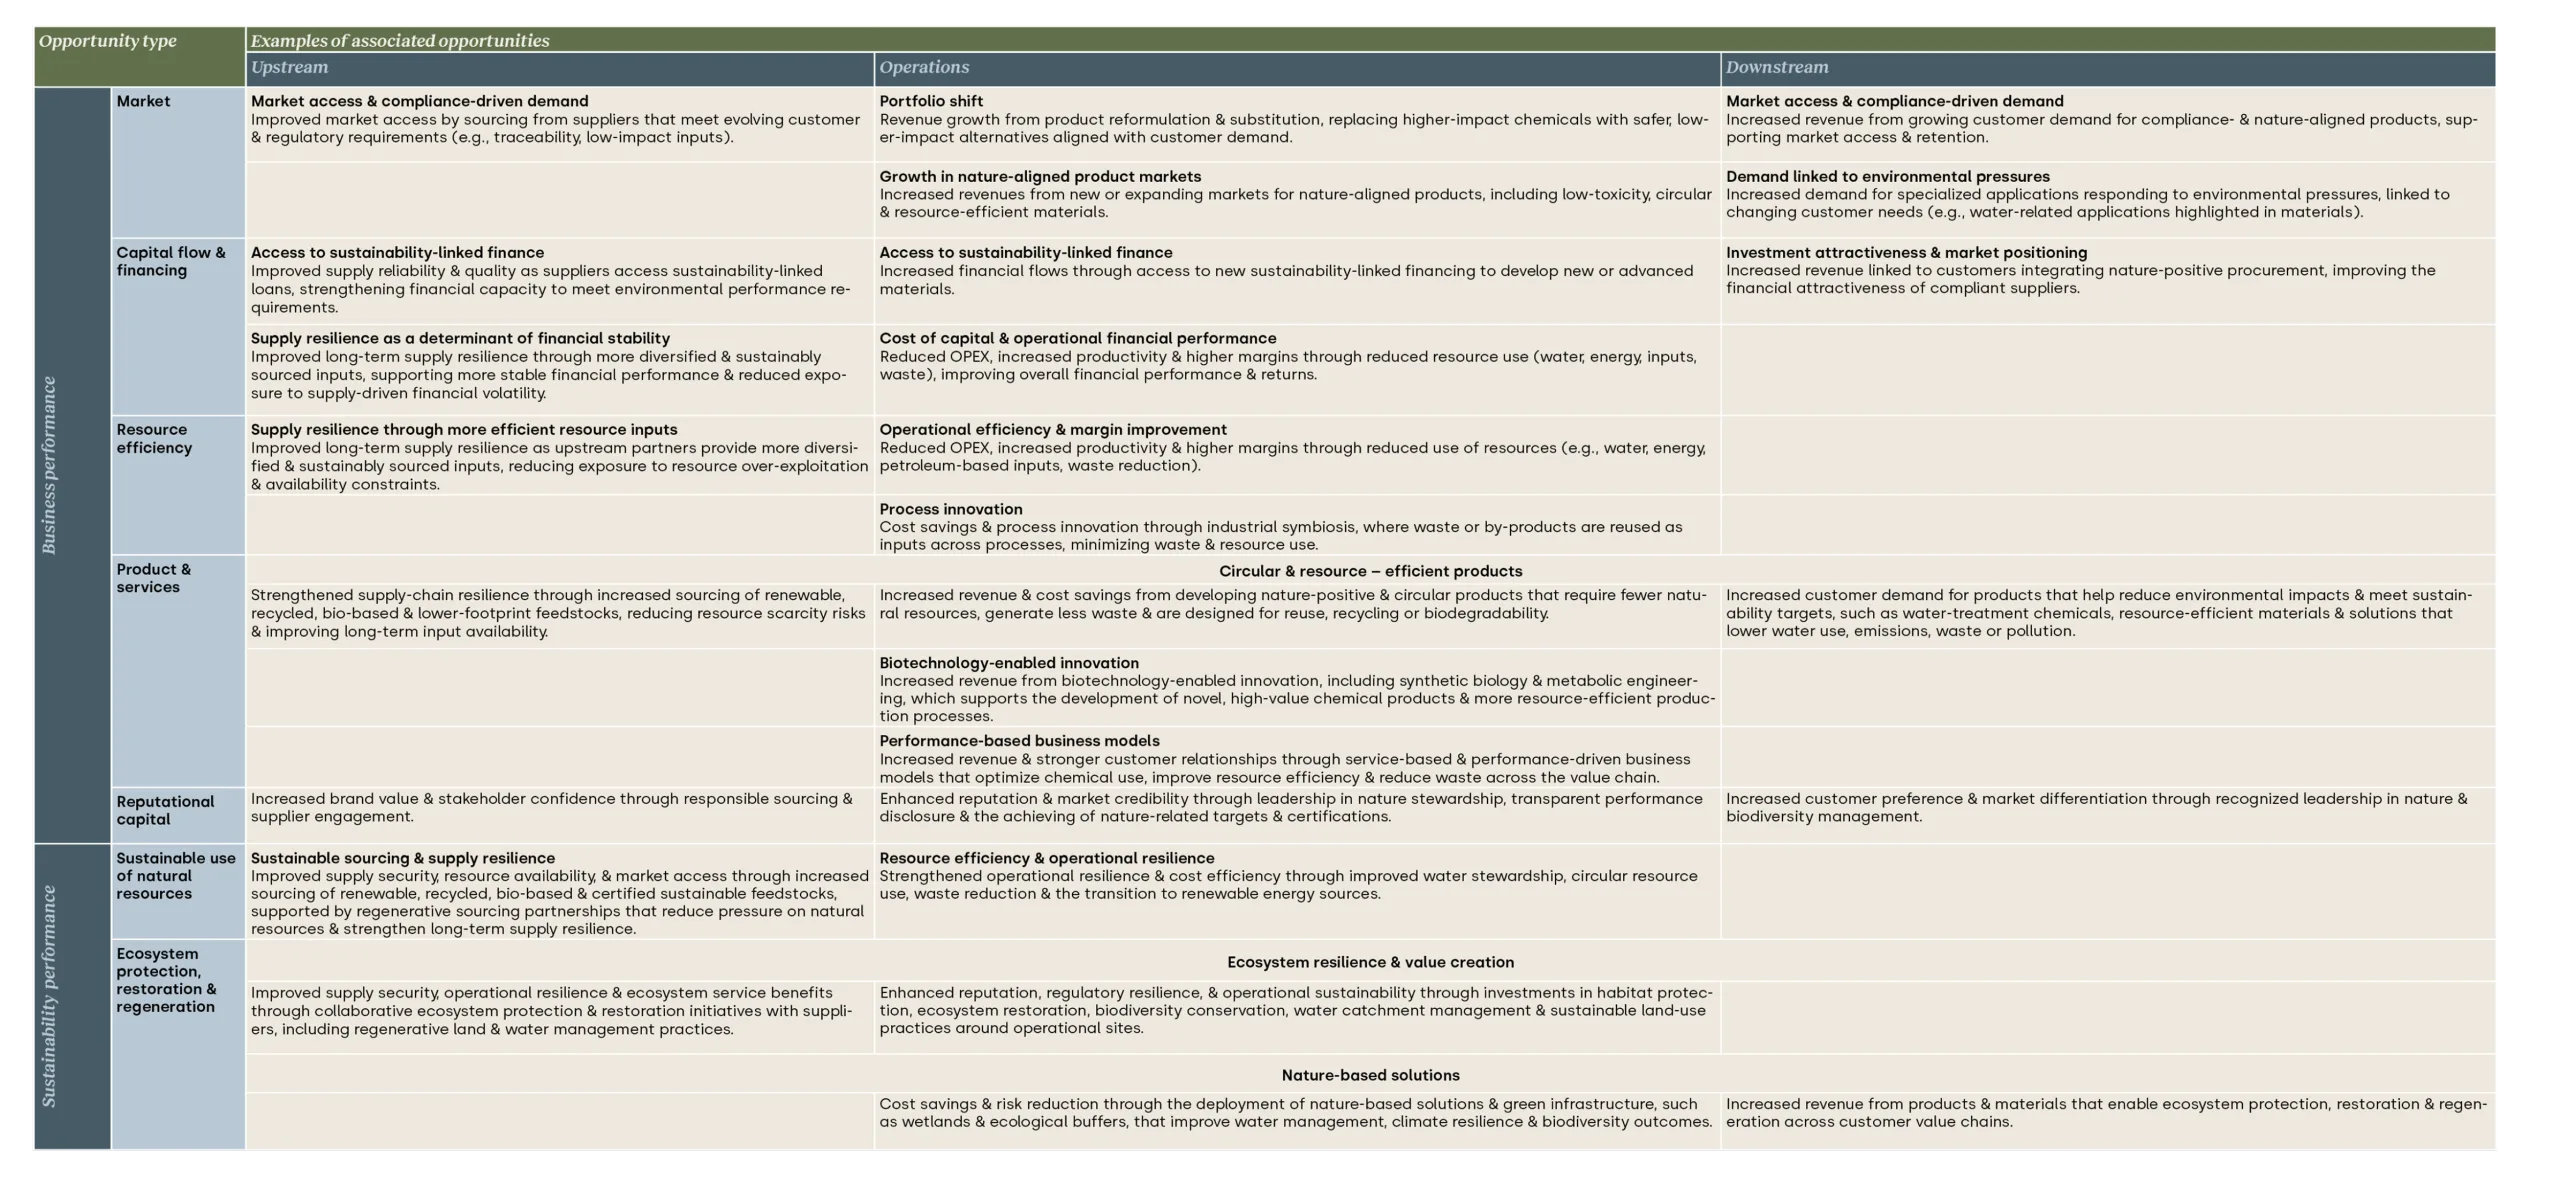
Nature-related issues can affect every part of a business –from physical and operational disruptions to transition pressures like new regulations, litigation and reputational risk, and even systemic threats as ecosystems start to fail. Companies that respond proactively by transforming business models, products, services and investments can leverage those same forces. They can gain a competitive edge, strengthen investor and stakeholder confidence, and build the operational resilience needed to thrive in a changing world. The table below outlines examples of key risks and opportunities for the chemical sector, based on the TNFD framework.
Further reading
For more technical details, refer to the Methodology page.